Our Most Recent Show
Retirement Milestone Ages: EDU #2639
If you would prefer not to learn about Jim's upcoming drive to Ohio and the family change of plans also sending him to Massachusetts, you can skip to (10:00).
Chris's Summary
Jim and I walk through retirement milestone ages, from age 21, when a minor child beneficiary's stretch gives way to the 10-year rule, through catch-up contributions, penalty-free withdrawal ages, Social Security survivor and retirement claiming ages, the IRMAA lookback at 63, Medicare at 65, QCDs at 70½, and RMDs at 73 or 75. We also cover an obscure age 75 RMD rule for pre-1987 403(b) contributions and the age 85 limit for starting a QLAC.
Jim's "Pithy" Summary
Chris and I work through a list of retirement milestone ages I've been holding onto for a while, and the first stop, age 21, is a deep one. Folks, the stretch IRA is the Black Knight from Monty Python and the Holy Grail. It's gravely wounded, but it's not gone. A minor child of the deceased IRA owner, an eligible designated beneficiary, or as I call it, an eligible human, can still stretch until 21. Then the 10-year rule applies, and Chris and I guessed wrong on what happens next. I checked with the Ed Slott Group, and the answer comes down to one phrase: at least as rapidly.
Then we hit catch-up contributions at 50, including a new Roth rule this year that some listeners call a loophole. I don't. We cover the carve-out that lets public safety employees skip the 10% early withdrawal penalty at 50, and the rule of 55, including a strategy the IRS has implicitly blessed. And then there's the super catch-up. Folks, I have no idea what Congress was thinking. An extra $3,250 a year in your 60s is not going to fix anybody's retirement. Let people in their 20s and 30s put more in, where it can compound. Chris brings in the Social Security and IRMAA ages, including a disabled surviving spouse rule that taught both of us something new.
At 70½, QCDs can help at the margins when a big RMD threatens an IRMAA tier. I make Chris guess an obscure age 75 rule tied to 403s, and he earns a B+. Then he pulls out one I totally missed at 85: QLACs. I give Treasury credit here, not Congress, and I explain why we're a little softer on QLACs than on other deferred income annuities.
About the Show

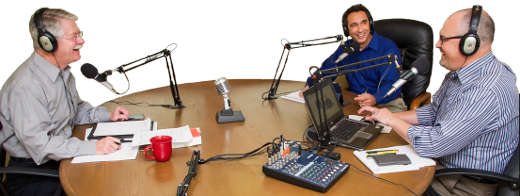
What do you get when you combine a TALENTED CFP® PROFESSIONAL with a well-informed COLLEGE FINANCE INSTRUCTOR? If you mix in relevant financial information and a healthy dose of humor you get the Retirement and IRA Show®, an informative, educational and entertaining podcast program focused on retirement topics.
Search
Looking for more information on a specific topic? Use the Search feature to find information on this site and Jim Saulnier & Associates, LLC business site.
 Send Us a Question
We’ll answer it on the show! Please include a phone # or email address and we’ll let you know when your question will air.
"*" indicates required fields


